Selling internationally involves much more than moving a parcel from one country to another. Every cross-border order raises critical operational and legal questions: Who is responsible for clearing the goods through customs?
Who collects and remits local VAT or GST? Who processes the customer’s payment? And who is legally recognized as the seller?
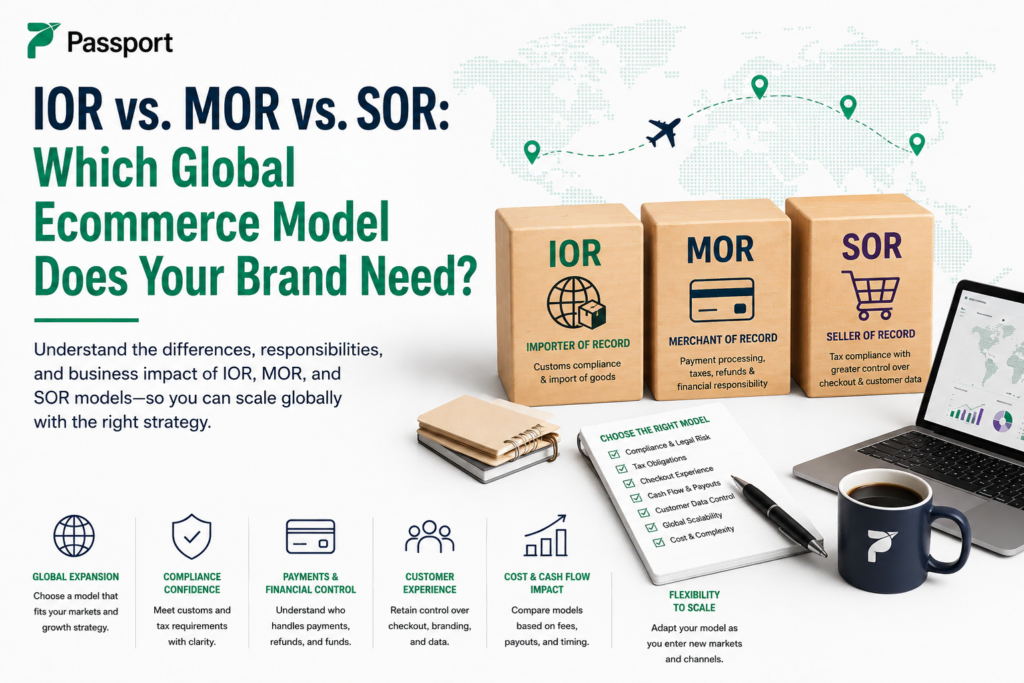
The answers often involve an Importer of Record (IOR), Merchant of Record (MOR), Seller of Record (SOR) — or a strategic combination of these roles. Although these titles sound similar and are often conflated, they are not interchangeable. Each role answers a distinct legal, financial, or operational requirement in cross-border commerce.
This guide breaks down how the three models differ, where their responsibilities overlap, and how your ecommerce brand can choose the right structure to scale globally with speed and compliance.
IOR vs. MOR vs. SOR at a Glance
Responsibilities Comparison Table
What Is an Importer of Record (IOR)?
An Importer of Record (IOR) is the party legally responsible to customs for goods entering a country, including their declaration, classification, duties, and import taxes.
In simple terms, the IOR is the party customs authorities hold accountable when goods enter a country.
Depending on the shipment structure, the IOR may be:
- The ecommerce brand
- A local entity
- A distributor
- A third-party compliance provider
- A logistics partner acting on behalf of the importer
In Passport’s standard cross-border model, the consumer is the Importer of Record. In Seller of Record markets, Passport’s tax ID is included in the shipment data, but that makes Passport accountable for VAT/GST on low-value goods, not the importer. The IOR and the party responsible for tax can be different entities.
Practical Example: A U.S.-based direct-to-consumer brand ships an order to a shopper in Canada. The designated IOR is the entity identified to Canadian customs as accountable for the import declaration, tariff classification, duty payment, and regulatory recordkeeping.
The Importer of Record is just one part of the broader international ecommerce operating model. Brands also need to decide who will act as the Merchant of Record (MOR) or Seller of Record (SOR) depending on how they want to manage payments, tax liability, and customer transactions. Learn more in our guide to Merchant of Record vs. Seller of Record.
For a deep dive, read our Importer of Record guide.
If you import into the U.S., Executive Order 14411 is tightening who can serve as Importer of Record. See how EO 14411 changes who can act as a U.S. Importer of Record.
What is a Merchant of Record (MOR)?
A Merchant of Record (MOR) is the legal seller in the customer transaction. It processes the payment, appears on the card statement, collects and remits VAT/GST, and handles refunds and chargebacks.
[Customer] ──► Payment & Order ──► [Merchant of Record] ──► Net Revenue (minus fees) ──► [Brand]
Key Responsibilities
* Processing customer payments and directly managing payment gateway operations.
* Serving as the recognized merchant (its name appears on customer credit card and bank statements).
* Collecting, reporting, and remitting relevant VAT, GST, or sales tax obligations.
* Managing customer financial disputes, chargebacks, and issuing refunds.
* Transferring net sales revenue to the merchant after accounting for taxes, processing fees, and service costs.
Control & Cash Flow Implications
Because an MOR sits directly inside the payment flow, using an MOR can affect your cash flow timing, as payouts occur after the provider processes deductions. Additionally, MORs aggregate transaction volumes across clients, meaning taxes are typically applied from day one on all orders. This setup means brands may miss out on country-specific registration thresholds or exemption limits that would otherwise delay tax collection requirements.
Practical Example: A customer in the UK buys a jacket on a U.S. brand’s storefront. The MOR processes the credit card payment, calculates and collects UK VAT, appears on the customer’s credit card bill, handles chargeback risk, and remits the remaining revenue to the brand on a scheduled settlement cycle.
For a deep dive read our MOR article: Merchant of Record: Essential Insights for International Ecommerce
What is a Seller of Record (SOR)?
A Seller of Record (SOR) is the legal seller for indirect-tax purposes. It registers for, files, and remits VAT/GST, while the brand keeps its checkout, payment processor, and customer funds.
┌──► Direct Payment & Funds ──► [Brand]
[Customer] ──► Checkout Order ────┤
└──► Tax Data & Filings ──────► [Seller of Record]
Key Responsibilities
* Managing non-resident VAT/GST registrations across target international markets.
* Filing tax returns and remitting collected indirect taxes to local authorities.
* Issuing tax-compliant local invoices and required disclosures.
* Monitoring country-specific sales thresholds so taxes are collected and remitted only when legally required.
* Liaising with foreign tax offices to address compliance inquiries or audits.
Control & Operational Implications
Under an SOR framework (such as Passport’s Seller of Record® model), the brand maintains its existing payment processor (e.g., Stripe, Shopify Payments), retains immediate access to sales revenue, sets its own pricing strategies, and retains full ownership of first-party customer data.
Example: A U.S. supplement brand expands into Australia. Using an SOR model, the brand processes customer payments directly through its existing payment gateway. The SOR monitors Australia’s $75,000 AUD registration threshold. Once passed, the SOR handles all local GST reporting and remittance on behalf of the brand, without disrupting the brand’s checkout or delaying its cash flow.
For more information read: Seller of Record (SOR): What It Is & How It Simplifies Ecommerce Tax Compliance
The Biggest Differences Between IOR, MOR, and SOR
Customs Responsibility
The IOR is the sole party accountable to customs authorities for physical entry, tariff valuation, HS classification, and admissibility. Neither MOR nor SOR models automatically define who acts as the Importer of Record; customs entry arrangements must be explicitly outlined in logistics contracts. A customs broker may file the declaration and pay tax to customs on the importer’s behalf without becoming the importer or the seller.
Checkout and Payment Control
The IOR plays no role in checkout design or payment stack management. An MOR generally takes control of payment processing, merchant descriptors, and checkout financial flows. An SOR leaves payment processing, checkout UI, and transaction control entirely with the brand.
VAT and GST Compliance
An IOR accounts for import VAT/GST at the border during customs entry. MOR and SOR providers manage point-of-sale indirect taxes (VAT/GST). However, while MORs typically collect taxes on all orders immediately due to aggregated volume, SORs can optimize compliance around country-specific registration thresholds, ensuring taxes are only paid when legally triggered.
Customer Relationship
The IOR operates entirely behind the scenes. The MOR acts as the legal seller on payment descriptors and invoices, frequently interacting directly during billing disputes or refunds. An SOR operates invisibly on tax compliance, keeping your brand front-and-center throughout the customer lifecycle.
Cash Flow
IOR services do not handle sales revenue. Under an MOR setup, sales funds flow to the MOR first, which deducts fees and taxes before remitting net payouts on a fixed schedule. Under an SOR setup, customer funds go directly into your account instantly via your payment gateway.
Scope of Responsibility
IOR: Customs and physical clearance layer.
MOR: Payment processing, transaction financial liability, and tax layer.
SOR: Indirect tax registration, filing compliance, and legal seller layer.
Are IOR, MOR, and SOR Competing Models?
A common misconception in global ecommerce is that brands must select just one of these acronyms to run their international operations.
In reality, IOR, MOR, and SOR are complementary frameworks that address different layers of a cross-border sale. They frequently coexist within a brand’s tech and operational stack:
* A brand may use an IOR for physical customs clearance alongside an MOR for payment handling and tax filings.
* A brand may pair an IOR for customs clearance with an SOR for indirect-tax filings while processing customer payments independently.
* A single partner (like Passport) can fulfill multiple roles depending on destination market regulations, sales channels, or shipment structures.
Scenario Deep Dives: Combining Operating Models
When Might a Brand Need Both an IOR and an SOR?
A brand pairs an IOR with an SOR when it wants customs and tax covered but wants to keep its own checkout, payment processor, and customer data. In Passport’s standard cross-border model, the consumer is the Importer of Record. For orders above a market’s low-value threshold, import VAT/GST and duties are accounted for at the border, billed to the brand under DDP. For low-value orders in SOR markets, Passport acts as Seller of Record: VAT/GST is collected at checkout, Passport’s tax ID travels in the shipment data, and Passport reports and remits the tax through a tax return.
Practical Example: A U.S. apparel brand sells a £90 jacket to a UK customer. Because the order is £135 or less, UK VAT is collected at checkout and Passport reports it to HMRC as Seller of Record. The customer is the importer, and the brand’s payment processor receives the funds directly. A £400 coat to the same customer is above the low-value threshold, so import VAT and duty are handled at the border instead.
This combined setup works best for brands that want compliance coverage without handing over checkout, payments, or customer data.
When Might a Brand Need Both an IOR and an MOR?
A brand pairs an IOR with an MOR when it wants to outsource the whole transaction layer as well as customs. The MOR is the legal seller in the customer transaction: it processes the payment, appears on the card statement, collects and remits point-of-sale VAT/GST, and handles refunds and chargebacks. The IOR is accountable to customs for the goods themselves. Each order still follows only one tax path: point-of-sale VAT/GST at checkout for low-value goods, or import VAT/GST and duties at the border for everything above the threshold.
Practical Example: A U.S. skincare brand sells an A$120 order to a customer in Australia through an MOR. Because the MOR aggregates sales across all its clients, it collects 10% GST at checkout from the first sale, even though the brand’s own Australian sales are well below the A$75,000 registration threshold. The MOR appears on the customer’s card statement and pays the brand its net revenue on a settlement cycle. An A$1,200 order to the same customer is above the A$1,000 low-value threshold, so GST and duty are handled at the border on the import side instead.
This combined setup works best for brands that want a single provider to own payments, disputes, and tax, and are willing to trade checkout control and cash-flow timing for that simplicity.
Which Model Fits Your Expansion Strategy?
Choose or Appoint an IOR When:
* You need a locally eligible legal entity to declare goods at destination customs.
* You lack foreign business registrations or local import credentials.
* Your shipments require formal entry declarations, tariff classifications, or product admissibility checks.
*You need to import and hold inventory locally to support marketplace fulfillment programs, such as Amazon FBA or TikTok Shop.
Consider an MOR When:
* You want a single partner to take complete responsibility for payments, chargebacks, and tax compliance.
* You prefer operational simplicity over maintaining custom payment stack configurations.
* You want to rapidly open new markets without managing foreign currency merchant accounts.
Consider an SOR When:
* Your main obstacle is foreign VAT/GST compliance and non-resident tax filing chaos.
* You want to keep your existing checkout UI, preferred payment processor, and direct cash flow access.
* You want to leverage country-specific registration thresholds to optimize when you begin paying indirect taxes.
* First-party customer data and pricing autonomy are vital to your business model.
Decision Matrix for Ecommerce Brands
How Passport Supports Global Operating Models
Navigating cross-border growth shouldn’t force you into a rigid, one-size-fits-all model. Passport helps brands navigate international expansion by offering flexible cross-border solutions — including global parcel shipping, landed-cost checkout technology, Importer of Record expertise, and both Seller of Record (SOR®) and Merchant of Record (MOR) services.
Whether you want to completely outsource payments and compliance through a Merchant of Record or preserve your existing payment processor, cash flow, and storefront using Passport Seller of Record®, Passport provides the infrastructure to scale seamlessly.
Evaluating your global growth strategy? Contact Passport today to determine the right combination of IOR, MOR, and SOR capabilities for your target markets.
Authored by Thomas Taggart
Head of Global Trade | Passport
Thomas Taggart is a cross-border commerce leader with more than 20 years of experience in international shipping and regulatory affairs. As the Head of Global Trade, Thomas helps ecommerce brands go global by simplifying international trade, tax, and product compliance issues. Prior to Passport, he brought international shipping solutions to market through multiple roles in UPS’s product development organization.
Frequently Asked Questions
Is an Importer of Record the same as a Merchant of Record?
No. An Importer of Record (IOR) handles customs clearance, documentation, and product admissibility when goods physically enter a country. A Merchant of Record (MOR) manages the customer’s financial transaction, including payment processing, transaction-level indirect taxes, refunds, and disputes.
Is a Seller of Record the same as an Importer of Record?
No. A Seller of Record (SOR) takes responsibility for specified selling and indirect-tax obligations (like VAT/GST registrations and filings). An Importer of Record is responsible for legal customs entry and duty compliance at the border. A single partner may perform both roles depending on the contract.
What is the main difference between MOR and SOR?
The main difference is payment and checkout control. An MOR typically processes customer payments, acts as the merchant on bank statements, and controls the payment transaction flow. An SOR manages indirect-tax compliance while allowing the brand to keep its existing payment processor, receive customer funds directly, and retain ownership of checkout data.
Do ecommerce brands need an IOR, MOR, and SOR?
Not necessarily. Requirements depend on your target markets, shipping model, checkout structure, and internal resources. Some brands only need an IOR for customs, while others combine an IOR with an SOR or MOR to handle both physical and financial compliance.
Can the same company act as both IOR and MOR?
Yes. When supported by regional regulations and provider capability, a partner can serve as both IOR (handling customs clearance at the border) and MOR (processing payments and filing taxes).
Can the same company act as both IOR and SOR?
Yes. A partner can serve as the Importer of Record for customs entry while acting as the Seller of Record for local VAT/GST compliance, all while leaving payment processing in the brand’s hands.
Who handles VAT and GST: the IOR, MOR, or SOR?
There are two kinds of VAT/GST on a cross-border order, and each order follows only one path. Import VAT/GST is accounted for at the border during customs clearance and applies to orders above a market’s low-value threshold. Point-of-sale VAT/GST applies only to low-value goods: it’s collected at checkout and reported on a tax return by the MOR or SOR. Under Passport’s Seller of Record model, Passport is accountable for point-of-sale VAT/GST even though the consumer is the importer.
Who controls checkout under each model?
The IOR has no involvement in checkout. An MOR often influences or controls checkout and payment configurations. Under an SOR model, the brand retains complete control over its checkout UI, payment processors, and customer experience.
Which model gives a brand the most payment control?
The SOR structure provides the most payment control. It allows brands to use their existing payment gateways, receive customer funds directly without intermediary delays, and retain full control over customer pricing and data.
Is an MOR always better for global expansion?
No. While an MOR provides a broad, outsourced solution, it requires giving up payment control, accepting settlement delays, and potentially paying taxes from day one on low-volume markets. Brands seeking compliance support without sacrificing checkout flexibility often prefer an SOR model.